TL;DR: AI underwriting software automates document review, credit scoring and risk selection across insurance and lending. Kolena is best for document-heavy underwriting review, Zest AI fits automated consumer credit decisions, Federato fits portfolio-steered risk selection, and Ocrolus fits cash flow and income verification.
What Is AI Underwriting Software?
AI underwriting software automates the evaluation, risk assessment, and document analysis processes for lending and insurance institutions. These solutions process information such as applications, financial records, claims history, credit data, and third-party data to support underwriting decisions.
AI underwriting software software can automate tasks such as data extraction, risk classification, fraud detection, pricing, and eligibility checks. Models identify patterns in historical and current data, while predefined business rules enforce underwriting policies and regulatory requirements.
How AI underwriting software works:
- What actually gets automated: Document intake and parsing, field extraction, cross-document reconciliation, model population, metric calculation (NOI, cap rate, DSCR, IRR), and first-pass risk flagging, can be fully automated by state of the art solutions.
- What is not automated: Market assumptions and comp selection are only partially automated; where the platform supplies benchmarks but the analyst chooses. Capital structure, business plan, and the go/no-go recommendation is done by a human real underwriter.
- CRE underwriting AI for equity acquisitions and debt teams: Equity-side workflows need lease abstraction with multi-amendment consolidation, rent roll audits against actual lease text, and IRR/DCF input population. Debt-side workflows need borrower file cross-checking, loan term extraction, DSCR inputs, and funding-ready credit packages. Most platforms pick one side.
- AI commercial real estate underwriting has additional requirements: batch processing across full deal packages rather than single documents, inline citations that survive an investment committee challenge, and template mapping into the firm's existing Excel model.
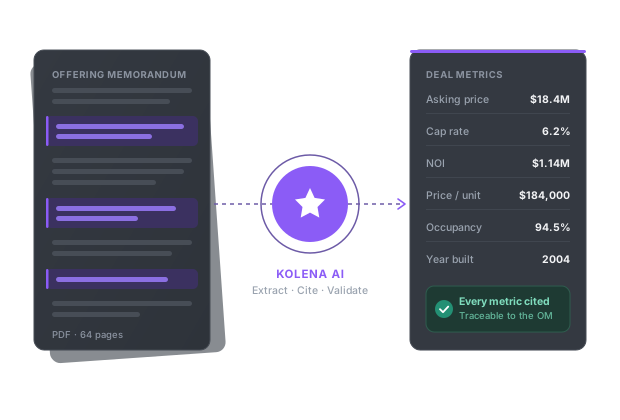
- What determines accuracy: Accuracy in AI for real estate underwriting depends on the solution architecture. Platforms that reach 90-95%+ on lease abstraction do three things: validate extractions across multiple models and return results only when those models agree; read tables as tables rather than flattening them into text and reconstructing them; and cite source page for every field so a human can verify them.
Analyze your first offering memo in minutes with AI
AI Underwriting Software at a Glance
The table below summarises the key differences between the platforms covered in this guide, including what each one is built for and where its boundaries sit. Each solution is explored in more detail in the sections that follow.
Category | Solution | Best For | Key Strengths | Things to Consider |
|---|---|---|---|---|
AI document and financial analysis engines | Kolena | Document-heavy underwriting and claims review | Cited, confidence-scored extraction from any file type | Sits alongside rating and core systems |
AI document and financial analysis engines | Ocrolus | Cash flow and income underwriting for lenders | Bank statement, pay stub and tax form analysis with fraud checks | Extraction layer; decisioning happens downstream |
AI document and financial analysis engines | V7 Go | Submission ingestion and triage for specialty lines | Playbooks for SOVs, loss runs and ACORD forms | Horizontal platform across several industries |
AI document and financial analysis engines | Instabase AI Hub | Enterprise document workflows in underwriting and claims | Broker submission, loss run and bordereau processing | Enterprise pricing and navigation learning curve |
Credit decisioning and scoring models | Zest AI | Automated consumer credit decisions | Custom risk models with fair lending measurement | Scoped to US consumer lending |
Credit decisioning and scoring models | Upstart | Lenders adding AI-underwritten consumer volume | Large origination dataset, high automation rate | Marketplace model rather than self-run software |
Credit decisioning and scoring models | Scienaptic AI | Credit unions automating the full decision string | Underwriting, fraud, pricing and compliance in one call | Built around US credit union lending |
Credit decisioning and scoring models | Taktile | Risk teams that want to own decision logic | No-code decision flows with traceable agent reasoning | Needs upfront configuration and governance |
Credit decisioning and scoring models | Provenir | Decisions across the full customer lifecycle | Decisioning, data marketplace and case management combined | Interface and support flagged by some reviewers |
Risk selection and portfolio platforms | Federato | Carriers and MGAs steering selection to portfolio goals | Appetite guardrails embedded in live workflows | A core system decision, not a point purchase |
Risk selection and portfolio platforms | Sixfold | P&C and life underwriters wanting case recommendations | Appetite fit, risk signals and next best action | Underwriting only; claims sit elsewhere |
Risk selection and portfolio platforms | hyperexponential | Specialty and reinsurance teams pricing complex risk | Actuarial pricing models wired into underwriting | Assumes actuarial capacity to build models |
Risk selection and portfolio platforms | Gradient AI | Insurers scoring risk and claim severity | Risk scores, severity prediction, portfolio stratification | Analytics layer that plugs into existing systems |
Key Benefits of AI Underwriting Software
AI underwriting software can improve underwriting speed, consistency, and data quality while keeping human review available for complex or high-risk cases. Key benefits include:
- Faster decisions: Automates data collection, analysis, and routine eligibility checks, reducing the time required to process applications.
- Less manual work: Extracts and validates data from documents and connected systems, reducing repetitive data entry and review tasks.
- More consistent decisions: Applies the same models and business rules across cases, helping reduce variation in routine underwriting decisions.
- Broader data analysis: Processes larger datasets and more variables than manual workflows can typically handle efficiently.
- Earlier risk detection: Identifies unusual patterns, inconsistencies, and risk indicators that may require additional review.
- Better case prioritization: Routes straightforward cases through automated workflows while directing exceptions and complex risks to underwriters.
- Portfolio visibility: Helps teams monitor exposures, concentrations, decision patterns, and risk across products or customer segments.
- Scalable operations: Allows organizations to process higher application volumes without increasing manual underwriting work at the same rate.
What AI Underwriting Software Does
Collects and Standardizes Underwriting Data
AI underwriting software gathers data from applications, uploaded documents, internal systems, credit bureaus, and third-party sources. It can extract relevant fields and convert information from different formats into a consistent structure for analysis.
The software can validate fields, identify missing values, and compare information across sources. This reduces manual data entry and helps underwriters work from a more complete and consistent dataset.
Assesses and Classifies Risk
AI models analyze applicant, financial, claims, credit, and exposure data to identify patterns associated with risk. Depending on the use case, the software may generate a risk score, assign a risk category, or estimate the probability of an event such as default or a claim.
These outputs support underwriting decisions rather than replacing underwriting policies. Organizations can combine model results with eligibility rules, risk appetite, and thresholds that determine whether a case is approved, declined, or referred for review.
Automates Underwriting Decisions and Workflows
AI underwriting software can automate routine decisions when applications meet predefined criteria. For example, it can approve low-risk cases, reject applications that fail eligibility requirements, or route complex cases to an underwriter.
Workflow automation can also assign cases, request additional information, and trigger follow-up tasks. This allows underwriting teams to spend less time processing straightforward applications and more time reviewing exceptions.
Detects Fraud and Data Inconsistencies
AI systems can compare information across applications, documents, historical records, and external data sources to identify unusual patterns. Examples include conflicting income figures, duplicate identities, suspicious transaction activity, or application details that differ from known records.
Detected anomalies can be assigned a risk indicator or sent for additional verification. The software does not establish that fraud occurred; it helps prioritize cases that require further investigation.
Supports Pricing and Terms
Underwriting software can use risk estimates alongside business rules to support pricing, coverage, credit limits, deductibles, interest rates, and other terms. Models can identify how specific risk factors relate to expected losses or repayment behavior.
Organizations can apply constraints around these recommendations to enforce pricing policies and regulatory requirements. Underwriters can then review cases where recommended terms fall outside normal thresholds or require additional judgment.
Monitors Underwriting Performance
AI underwriting platforms can track decisions, model outputs, overrides, losses, defaults, and other outcomes over time. This creates data that organizations can use to compare predicted risk with actual results.
Monitoring can also help identify model drift, changes in applicant populations, or differences in performance across segments. These findings can inform model validation, policy changes, and adjustments to underwriting thresholds.
Types of AI underwriting software
AI Document and Financial Analysis Engines
These tools extract and analyze underwriting data from documents such as financial statements, tax returns, bank statements, applications, and supporting records. They use technologies such as optical character recognition and natural language processing to turn unstructured documents into structured data.
They can also calculate financial ratios, detect inconsistencies, identify missing information, and compare figures across multiple documents. This reduces manual data entry and gives underwriters standardized information for risk assessment.
Credit Decisioning and Scoring Models
Credit decisioning and scoring models estimate the likelihood that a borrower will repay a loan or meet other credit obligations. They analyze factors such as payment history, debt levels, income, cash flow, and existing credit exposure to produce risk scores or recommended decisions.
These models can support automated approvals, declines, credit limits, pricing, and referrals for manual review. Lenders typically combine model outputs with business rules and policy requirements rather than relying on an AI-generated score alone.
Risk Selection and Portfolio Platforms
Risk selection and portfolio platforms help underwriters evaluate individual risks while considering their effect on the overall portfolio. They combine underwriting rules, predictive models, exposure data, pricing information, and an organization's risk appetite.
These platforms can monitor concentrations and exposures across industries, locations, products, or other segments. This allows underwriting teams to identify accumulating risks, apply portfolio limits, and make individual decisions within broader risk targets.
Why Generic AI Tools Fall Short: Dedicated AI Real Estate Underwriting vs. ChatGPT/Claude
General-purpose LLMs like ChatGPT or Claude have four specific failure modes on real estate underwriting work, and each one is a reason purpose-built real estate underwriting AI exists as a separate category:
- They can't handle batches: A lease review for a 150-tenant mall acquisition involves hundreds of documents, including leases, amendments, exhibits, rent rolls, T-12s. ChatGPT processes them one at a time and loses context between documents. Amendments break the chain entirely: the model doesn't know that amendment 4 supersedes amendment 2 on the rent schedule.
- They produce free-form output: Your underwriting model expects specific cells in specific places. A chat response forces the analyst to read it, find the relevant numbers, and copy them, re-introducing exactly the manual work the AI was supposed to eliminate.
- They hallucinate at scale: General LLMs are trained to be helpful, which means they make up plausible-sounding answers when context runs out. For a base rent number on a $50M acquisition, "plausible-sounding" is a financial error.
- They don't cite sources: When an underwriter asks "why is the year-three NOI projection $4.2M?" the answer needs to point back to the exact page of the exact lease. Free-form chat output doesn't.
Purpose-built, AI-native real estate underwriting software solves these by reading documents in structured batches, outputting to fixed templates, validating extractions across multiple models, and citing the source page for every number it produces.
Learn more about investment memo.
Notable AI Underwriting Software
How we selected these platforms: We shortlisted AI underwriting software based on document extraction and financial analysis depth, credit scoring and decisioning capability, risk selection and portfolio steering, explainability and audit trails, and how each product integrates with existing origination, policy administration and core systems.
AI Document and Financial Analysis Engines
1. Kolena
Best for: Document-heavy underwriting and claims review across insurance
Strengths: Cited, confidence-scored extraction from any document format
Things to consider: Sits alongside rating and core systems rather than replacing them
Kolena is an AI platform that automates document-heavy workflows in insurance, banking, financial services and real estate. In underwriting it handles loss runs, ACORD forms, risk profiling and compliance checks, converting the contents of submission packets into structured data that underwriters can work from directly.
The platform parses PDFs, spreadsheets, emails, scans and audio, detects document types automatically, applies business rules and cross-checks to each field, and returns outputs with reasoning, confidence scores and citations. Pre-built workflows for insurance can be deployed in hours and tailored to a team's own policy, compliance and reporting requirements.
Key features include:
- Risk profile analysis: Ingests underwriting factors, claim history and safety protocols and assembles them into a detailed risk assessment for the underwriter to review.
- Loss run analysis: Standardises loss run reports arriving from multiple carriers in different formats and years, then surfaces claim trends and exposures from the normalised data.
- Fraud and compliance monitoring: Analyses policy and applicant data to flag anomalies, and cross-references documents to catch missing evidence or inconsistent coverage terms.
- Operational insights: Searches company operations data, sanctioned-party lists and hazard grades so those checks happen inside the same workflow.
- Field-level validation with citations: Applies business rules and cross-checks to every extracted value, and attaches an explanation, a confidence score and a source-page citation to each result.
- Integrations and outputs: Pushes structured results into Excel, CRMs, SharePoint and other systems, with connections to Salesforce, Box, Drive, Yardi, MRI and VTS.
Limitations (based on publicly available sources):
- Scope of the platform: Kolena automates document analysis and workflow rather than rating, quoting or policy administration, so those functions remain in the existing core system.
- Configuration to internal standards: Agents are built around each team's own rubric and extraction template, which means some setup work before outputs match internal conventions.
- Pricing visibility: Pricing is not published, so cost has to be scoped directly with the vendor.
2. Ocrolus
Best for: Cash flow and income underwriting for lenders and mortgage teams
Strengths: Bank statement, pay stub and tax form analysis with fraud checks
Things to consider: Extraction layer only; decisioning still happens downstream
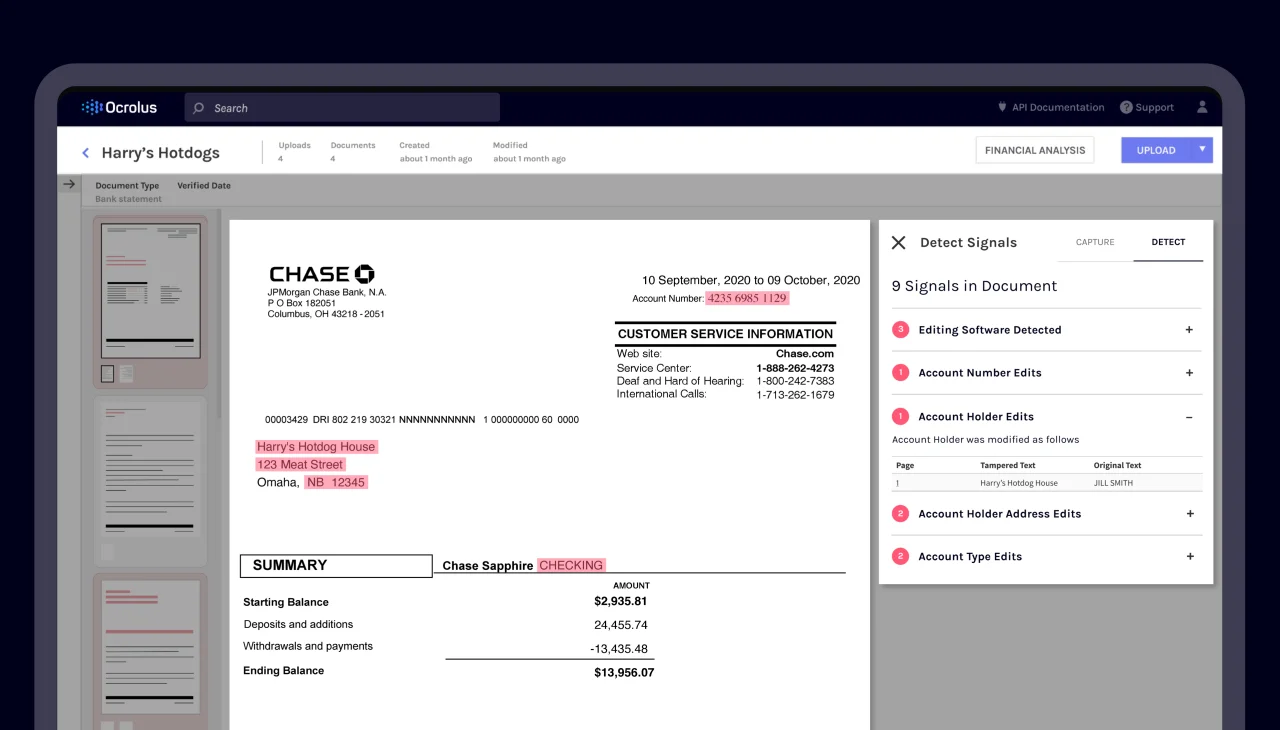
Ocrolus is a document automation and analytics platform for lenders. It converts financial documents and digital data into credit analytics, with specialisations in bank statements, pay stubs and tax forms, and states accuracy above 99% on document understanding.
The product is organised around vertical solutions. Small business funders use cash flow analysis to measure revenue and debt capacity, while mortgage lenders use income calculations and condition management. Results are delivered through an API or a dashboard and feed into existing loan origination systems.
Key features include:
- Document understanding: Classifies and extracts data from bank statements, pay stubs and tax documents, handling parseable PDFs, scans and photographs of financial paperwork.
- Fraud detection: Identifies fabricated or altered documents, inconsistencies between data points, and other risk signals present in a borrower's submitted file.
- Cash flow analysis: Measures revenue and debt capacity for small business funding decisions, turning transaction-level detail into credit analytics.
- Income calculations: Evaluates income across different borrower types for mortgage underwriting, covering salaried, variable and self-employed profiles.
- Inspect: Creates and clears underwriting conditions automatically so files move through review without manual condition tracking.
- API and LOS delivery: Available through API and dashboard, with integrations that deliver output into existing loan origination workflows.
Limitations (as reported by users on Software Advice):
- Processing time on complex files: Turnaround can be longer on complicated bank statements, which slows throughput for teams working to same-day decision targets.
- Extraction gaps: Some reviewers report missed details on financial documents, leading to manual double-checking of the output.
- Cost relative to output: Reviewers have questioned the value for money where manual verification is still required after processing.
- Communication on product changes: New analytics releases and the accompanying documentation have not always been communicated proactively to users.
Source: Ocrolus
3. V7 Go
Best for: Submission ingestion and triage for specialty insurance lines
Strengths: Line-specific playbooks for SOVs, loss runs and ACORD forms
Things to consider: Horizontal platform spanning insurance, finance and real estate
V7 Go is an agentic workflow layer that turns insurance documents into structured operational data. It covers submission ingestion, underwriting triage, policy review and claims processing, and processes underwriting submissions, broker emails, ACORD forms, exposure and catastrophe data, risk engineering reports and reinsurance contracts.
Work moves through a defined sequence of arrival, classification, extraction, checking, population and decision. V7 states the product is not a policy administration or claims system, but an intelligence layer that runs across underwriting, claims, compliance, reinsurance and back office tasks.
Key features include:
- Line-specific playbooks: Ships with playbooks for property, marine cargo, cyber, D&O and aviation, pre-trained on the document taxonomies and field structures each line uses.
- Specialty property extraction: The specialty property playbook pulls structured data from statements of values, COPE assessments, CAT zone schedules and builder's risk submissions.
- Connected evidence trail: Links files, data points and sources so any output can be traced back to the underlying document, with pricing, sanctions, claims and billing data connected in one layer.
- Market-standard outputs: Produces forms, bordereaux and reporting outputs, and generates underwriting and claims reports, memos and presentations that export to PDF, PPTX, Drive or SharePoint.
- Persistent state and long-horizon reasoning: Memory updates as policies, claims, exposures and assumptions change, and agents preserve context across multi-step workflows.
- Security controls: No training on customer data, end-to-end encryption, fine-grained access controls and audit logs across every workflow.
Limitations (based on publicly available sources):
- Not a system of record: V7 states the product is not a policy administration or claims system, so it layers over whatever core platform an insurer already runs.
- Knowledge hub limits: Each hub holds up to 1,000 items, and files cannot be moved between hubs by drag and drop.
- Supported file types: Document support covers PDF, DOCX, XLSX, CSV, JPG and PNG, so anything outside that list needs conversion first.
- Breadth across industries: The platform also serves private markets and real estate, so insurance depth depends on how far the available playbooks cover a given book.
Source: V7 Go
4. Instabase AI Hub
Best for: Enterprise document workflows across underwriting and claims
Strengths: Broker submission, loss run and bordereau processing at scale
Things to consider: Enterprise pricing and a learning curve on navigation
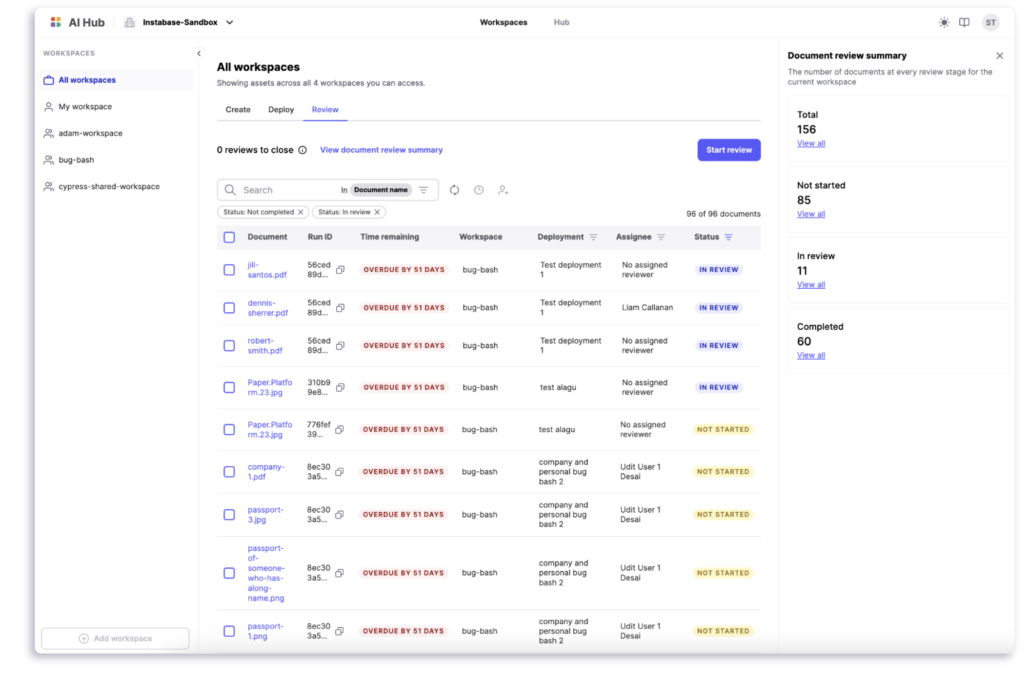
Instabase AI Hub automates document-heavy workflows across underwriting, claims and policy administration. It is built on a context-first architecture with agentic AI, and produces auditable outputs from broker submissions, loss runs, contracts and underwriting guidelines.
The insurance solution covers the intake side of underwriting in particular, splitting and validating data from submission packets before it reaches an underwriter. Workflows are configured rather than coded, which lets teams stand up new document processes without a development cycle for each one.
Key features include:
- Broker submission processing: Splits, extracts and validates data from broker submission packets so the information arrives structured rather than as an undifferentiated bundle of attachments.
- Loss run processing: Handles highly variable loss run reports, reducing the manual normalisation work that carrier-by-carrier formatting usually requires.
- Bordereau processing: Extracts relevant fields from bordereau documents, which supports delegated authority and MGA reporting workflows.
- Quotation processing: Pulls data out of complex quotation documents to shorten cycle time and increase the volume a broking team can handle.
- Fraud detection: Extracts, verifies and compares customer and claims data to identify potential fraud within the same workflow.
- Configurable document workflows: Lets teams configure AI-driven document workflows with enterprise reliability controls rather than building each pipeline from scratch.
Limitations (as reported by users on G2):
- Cost against alternatives: Multiple reviewers describe the expense as challenging relative to other document processing options.
- Navigation: The interface is described as unintuitive in places, with users reporting difficulty moving around the platform.
- Maintenance overhead: Reviewers mention maintenance issues affecting day-to-day use of the platform.
Source: Instabase
Credit Decisioning and Scoring Models
5. Zest AI
Best for: Automated consumer credit decisions at banks and credit unions
Strengths: Custom risk models with fair lending measurement built in
Things to consider: Scoped to US consumer lending, not commercial or insurance
Zest AI builds machine learning credit models for banks, credit unions and specialty lenders, with more than 600 active models in production. The platform automates underwriting decisions, adds application fraud detection, and reports on portfolio performance so lending policy can be adjusted between model cycles.
The company publishes figures for what its models change in a lending programme: 63% of decisions automated, a 20% lift in approvals without added risk, a 16% or greater reduction in risk at constant approval rates, and a 24% average lift across protected classes.
Key features include:
- AI-automated underwriting: Automates credit decisions so applications are approved or declined without manual review, with models built for each lender rather than applied off the shelf.
- Fraud detection: Screens for application fraud across the lending process, so identity and misrepresentation checks sit inside the same decision rather than in a separate tool.
- Lending intelligence: Produces portfolio reporting and applicant-level insight so lending strategy and policy can be adjusted using performance data rather than assumption.
- LuLu Pulse and LuLu Strategy: Reporting and strategy tools that let lending teams interrogate their own data and model behaviour.
- Fair lending measurement: Reports approval lift across protected classes, giving lenders a measured view of how model changes affect different applicant groups.
- Segment-specific deployment: Configurations for credit unions, banks and specialty lenders, each integrated into the institution's existing lending process.
Limitations (based on publicly available sources):
- Consumer credit focus: The platform serves US consumer lending at credit unions, banks and specialty lenders, and is not built for commercial credit or insurance underwriting.
- Model build dependency: Models are constructed per institution, so a lender needs sufficient historical performance data before deployment is viable.
- Integration requirement: Decisions run inside an existing lending process, which means integration work with the loan origination system is part of adoption.
- Pricing visibility: Pricing is not published and must be scoped with the vendor.
6. Upstart
Best for: Lenders adding AI-underwritten consumer loan volume
Strengths: Large origination dataset and high automation rates
Things to consider: Marketplace model rather than software you run yourself
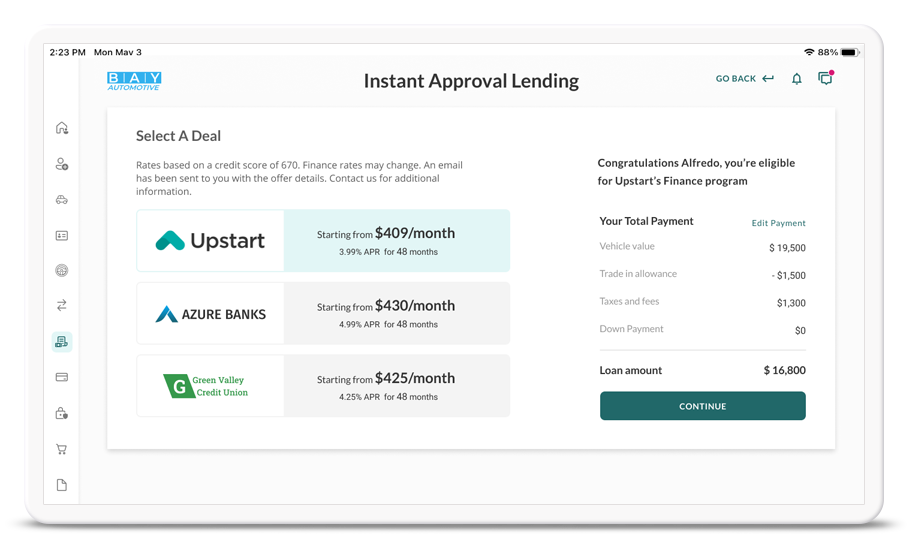
Upstart is an AI lending marketplace that connects banks and credit unions to consumer borrowers. The platform reports more than $61B in originations, over 4 million borrowers and more than 100 lending partners, with lenders configuring the credit box, risk tolerance and geographic focus of their programme.
Rather than selling a standalone model, Upstart runs the origination flow and delivers loans that meet each partner's stated parameters. The company reports 2.2 times more risk separation than FICO and that 91% of loans are fully automated end to end.
Key features include:
- Personal lending: Supplies personal loan volume configured to a lender's credit parameters, with borrowers routed to the lender's offer during the application flow.
- Auto lending: Two turnkey auto solutions running on automated digital experiences, covering both secured origination and refinance.
- Home lending: HELOC products structured for high utilisation and immediate interest income, delivered through a digital application process.
- Lender-branded and marketplace options: Partners can take volume through the marketplace or run a lender-branded experience, depending on how they want the programme to appear to borrowers.
- Borrower cross-sell: A marketing playbook plus integrated deposit account opening and switching technology for converting new borrowers into multi-product relationships.
- Compliance programme: Covers regulatory compliance, fair lending, data security and privacy, and safety and soundness across partner examinations.
Limitations (based on publicly available sources):
- Consumer credit only: The product range covers personal, auto and home equity lending, so commercial credit and insurance underwriting fall outside it.
- Marketplace dependency: Volume arrives through Upstart's channel rather than the lender's own origination funnel, which makes the programme dependent on that pipeline.
- Model oversight burden: Partner institutions carry the model validation and fair lending testing expected of AI-driven credit decisions in regulatory examinations.
- Macroeconomic sensitivity: Model performance is tied to credit conditions, and the company publishes macro-adjusted figures because loss expectations shift with the cycle.
Source: Upstart
7. Scienaptic AI
Best for: Credit unions automating the full consumer decision string
Strengths: Underwriting, fraud, pricing and compliance in one call
Things to consider: Built around US credit union lending and LOS integrations
Scienaptic AI runs credit decisioning for more than 160 lenders, mostly US credit unions, with over $160B in loans decisioned on the platform. Rather than returning a score, it returns a full decision string covering approve or decline, amount, term, price, counter-offer, adverse action reasons and audit trail.
Everything runs in a single API call from the lender's origination system, with identity, fraud, bureau and alternative data, underwriting, pricing and fair lending checks executed inside the same call and a response returned in under a second.
Key features include:
- Underwriting models on the lender's own book: Scorecards are built from each client's portfolio and augmented with more than 3,000 signals across bureau, banking and alternative data sources.
- FraudShield: Flags synthetic identities, bot attacks, bust-out patterns, credit washing and first-party fraud before an application reaches underwriting.
- LendSmart pricing: Deal-level vehicle pricing for direct and indirect auto, calibrated to each portfolio's yield targets at member and collateral level.
- Perpetual offers: Lifecycle pre-qualified offers for card line increases, refinance, HELOC and auto, refreshed against current bureau and behavioural data.
- Portfolio early warning: Monitors risk shifts at member, segment and book level, with models retrained on the lender's own performance data.
- Compliance engine: Runs disparate impact analysis on every model attribute, generates adverse action reasons automatically, and version-tracks model documentation with each release.
Limitations (based on publicly available sources):
- Segment focus: The platform is built around US credit unions and consumer lending products, so commercial credit and insurance underwriting are outside its scope.
- Integration prerequisite: Decisions run from the loan origination system, so the relevant LOS connection has to be in place before deployment.
- Deployment timeline: Typical implementation runs six to ten weeks, which is a project rather than a switch-on.
- Data history dependency: Scorecards are trained on each client's own book, so institutions with limited performance history have less to build from.
8. Taktile
Best for: Risk teams that want to own and iterate decision logic
Strengths: No-code decision flows with agents and traceable reasoning
Things to consider: Needs upfront configuration and governance to scale
Taktile is an agentic decision platform for financial institutions, covering onboarding, credit underwriting, AML and fraud investigation on the banking side, and underwriting and claims on the insurance side. Teams design and control how AI, business logic and human judgment interact within one environment.
The platform is organised around an AI Agent Manager, a Decision Engine, a Case Manager and a Context Layer, with pre-built agents and configurable solutions so a new decision strategy can be rolled out without building the workflow from first principles.
Key features include:
- Decision Engine: Lets risk and product teams build and iterate decision strategies directly, removing the engineering dependency that usually sits between a policy change and production.
- AI Agent Manager: Configures how agents operate against a firm's rules and processes, with guardrails that keep outputs inside defined business requirements.
- Traceable reasoning: Exposes the full chain of reasoning behind every output, with traceability and validation at each step rather than a single opaque result.
- Case Manager: Handles referred cases inside the platform, so investigations and manual reviews stay connected to the decision that produced them.
- Context Layer and Data Marketplace: Connects third-party data providers including Experian, Equifax, TransUnion, LexisNexis, Dun & Bradstreet, Middesk, Socure, Plaid and Codat without long integration projects.
- Performance monitoring: Real-time analytics across the customer lifecycle, with thresholds, workflows and human touch points tuned continuously against results.
Limitations (as reported by users on G2):
- Upfront configuration: Reviewers note that the flexibility comes with significant configuration and governance work to operate at scale.
- Parallel workflow handling: Users report constraints on running parallel flows within a single workflow for one entity.
- Analytics depth: Advanced analytics and certain customisation options are cited as areas where the platform is less developed than its core decisioning.
Source: Taktile
9. Provenir
Best for: Lenders running decisions across the full customer lifecycle
Strengths: Decisioning, data marketplace and case management combined
Things to consider: Interface and support quality flagged by some reviewers
Provenir is a decision intelligence platform used by more than 120 financial services providers across 60 countries, processing over 4 billion decisions a year. It consolidates data, AI models, analytics and decisioning agents into one governed environment rather than spreading them across separate tools.
The platform is structured in three connected layers: customer intelligence built from a lender's own historical data and outcomes, agentic decisioning that executes real-time decisions inside defined guardrails, and an optimisation cycle that validates strategy changes against production data before they go live.
Key features include:
- AI decisioning: Runs end-to-end decisions across credit risk, fraud, compliance and customer management, covering the customer journey rather than a single application moment.
- Customer intelligence layer: Builds proprietary models and analytics from a lender's own historical data and outcomes rather than applying generic market models.
- Optimisation cycle: Deploys strategy changes, validates them against real production data before going live, then refines through automated recommendations and continuous KPI monitoring.
- Data Marketplace: Provides on-demand access to global identity, fraud and credit data so new data sources can be added without a separate integration project.
- Case management: Refers and investigates decisions inside the platform, keeping manual review connected to the automated decision that triggered it.
- Low-code build environment: Cloud-native and low-code, so business teams can build, test and deploy decisioning strategies without relying on IT resources.
Limitations (as reported by users on G2):
- Interface design: Reviewers describe the user interface as dated relative to alternatives, with the visual design cited as a drawback.
- Workflow builder bugs: Users report issues affecting the workflow builder, including clipped or oversized text in node titles.
- Support responsiveness: Customer service is described by some reviewers as not meeting expectations.
- Competitive fit: Some enterprise reviewers felt the platform needs further development to match alternatives in the category.
Source: Provenir
Risk Selection and Portfolio Platforms
10. Federato
Best for: Carriers and MGAs steering risk selection to portfolio goals
Strengths: Appetite guardrails embedded in live underwriting workflows
Things to consider: A core system decision, not a point underwriting purchase
Federato is an AI-native core platform for carriers, MGAs and MGAAs covering policy administration, billing and payments, claims, product configuration, portfolio steering and partner portals. Its position is that decisioning should be built into the core system rather than added on top of a legacy one.
The distinguishing element for underwriting is Control Tower, which embeds portfolio strategy into live guardrails that shape submission decisions as they happen. Federato reports a 5.5 times increase in high-appetite bound policies, 90% of referrals automated and a 93% reduction in systems used.
Key features include:
- Control Tower: Embeds portfolio targets and guardrails into live workflows so growth and margin are shaped during execution rather than corrected after a quarter closes.
- Guardrails that persist past submission: Appetite rules stay active beyond the intake stage, with a record connecting stated intent to actual portfolio results.
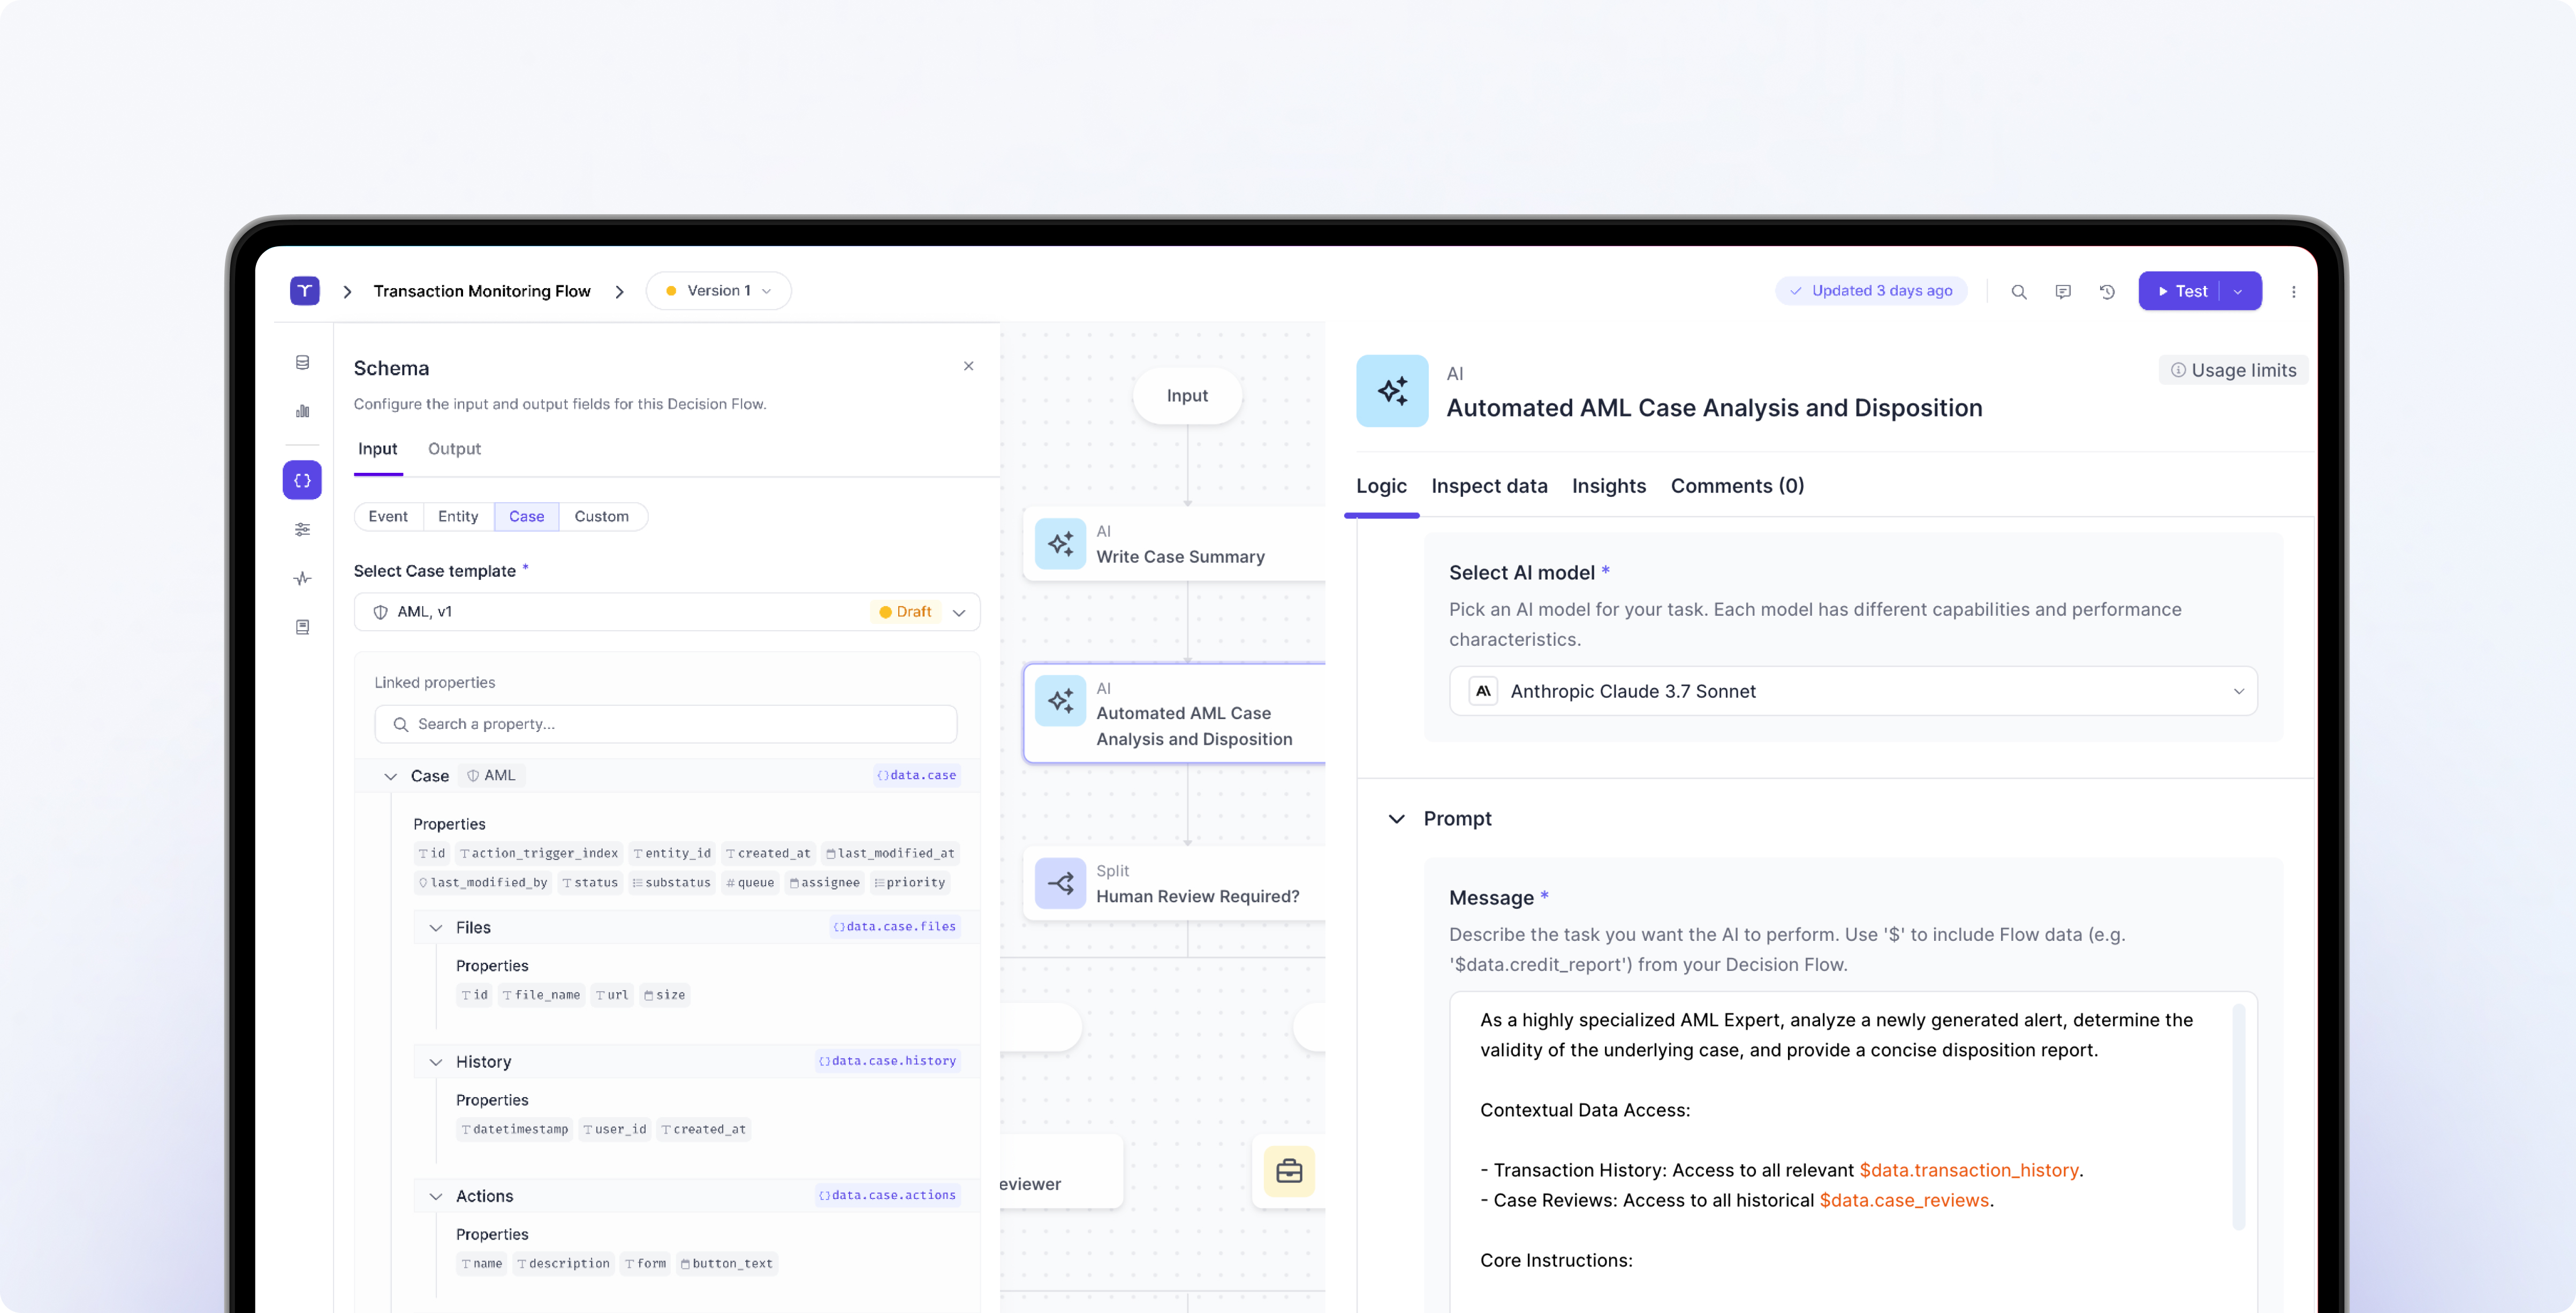
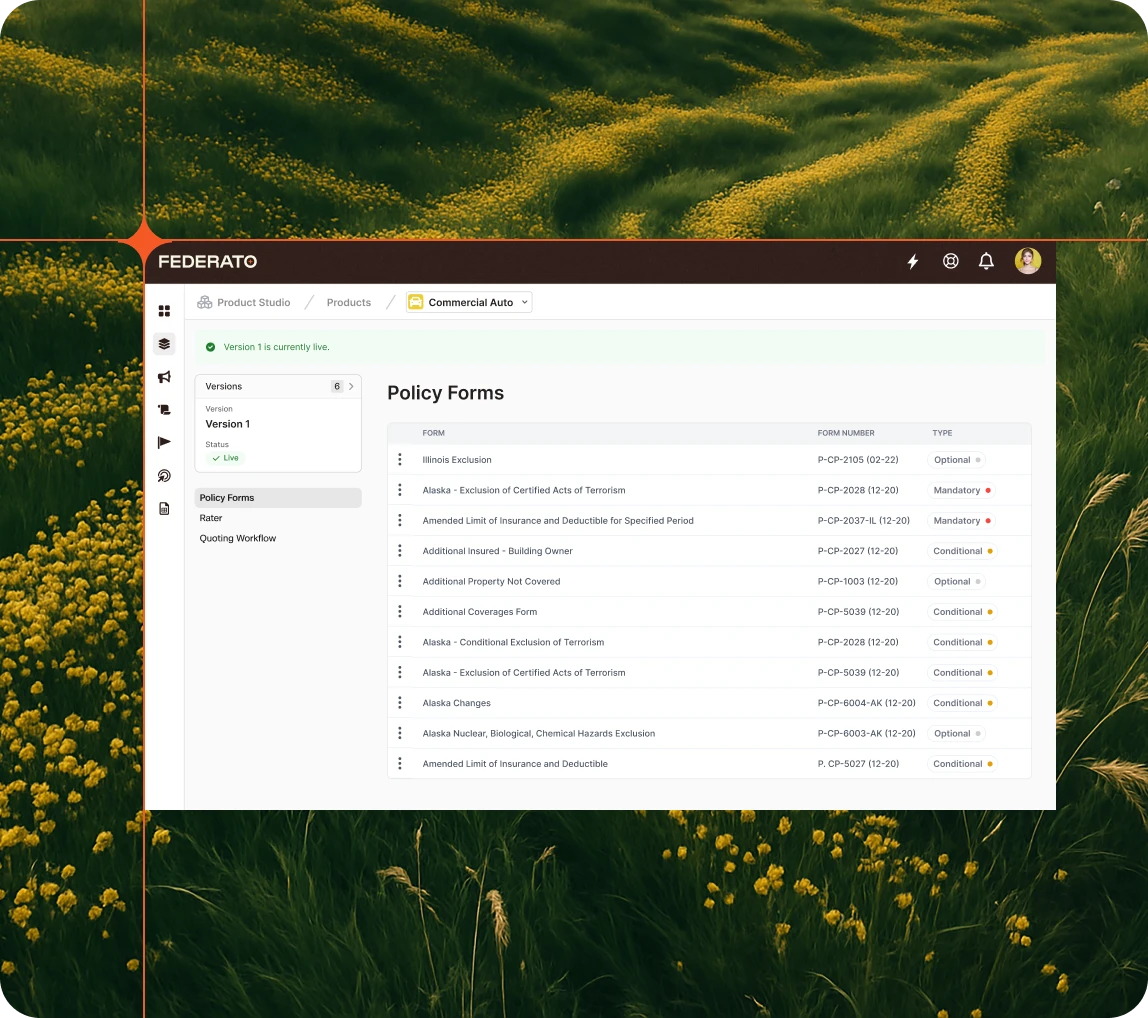
- Product Studio: Holds ratings, forms and eligibility in one place so a new product can be launched without rebuilding the same configuration in several systems.
- Agentic workflows across the lifecycle: Agents take on operational work at each stage, models adjust as underwriting decisions accumulate, and every recommendation remains auditable.
- Self-serve configuration: Configuration is version-controlled with change history and visible impact before deployment, so new programmes launch without a vendor release cycle.
- Partner Portals: Gives brokers and policyholders live access to quotes, policies, commissions, payments, coverage and claims in one place.
Limitations (based on publicly available sources):
- Scope of the decision: Federato positions itself as a core system replacement, which makes adoption a platform-level decision rather than an underwriting point purchase.
- Implementation timeline: The company states a first implementation typically runs 12 to 16 weeks, with roughly 8 weeks for each additional line of business after that.
- Dependent on defined strategy: Federato notes that its approach surfaces execution gaps but will not fix a flawed underwriting strategy, so a carrier needs a defined appetite to encode.
- Market focus: The platform serves P&C carriers, MGAs and MGAAs, so lending and consumer credit underwriting fall outside it.
Source: Federato
11. Sixfold
Best for: P&C and life underwriters wanting case-level recommendations
Strengths: Appetite fit, risk signals and next best action per submission
Things to consider: Underwriting only; claims and servicing sit elsewhere
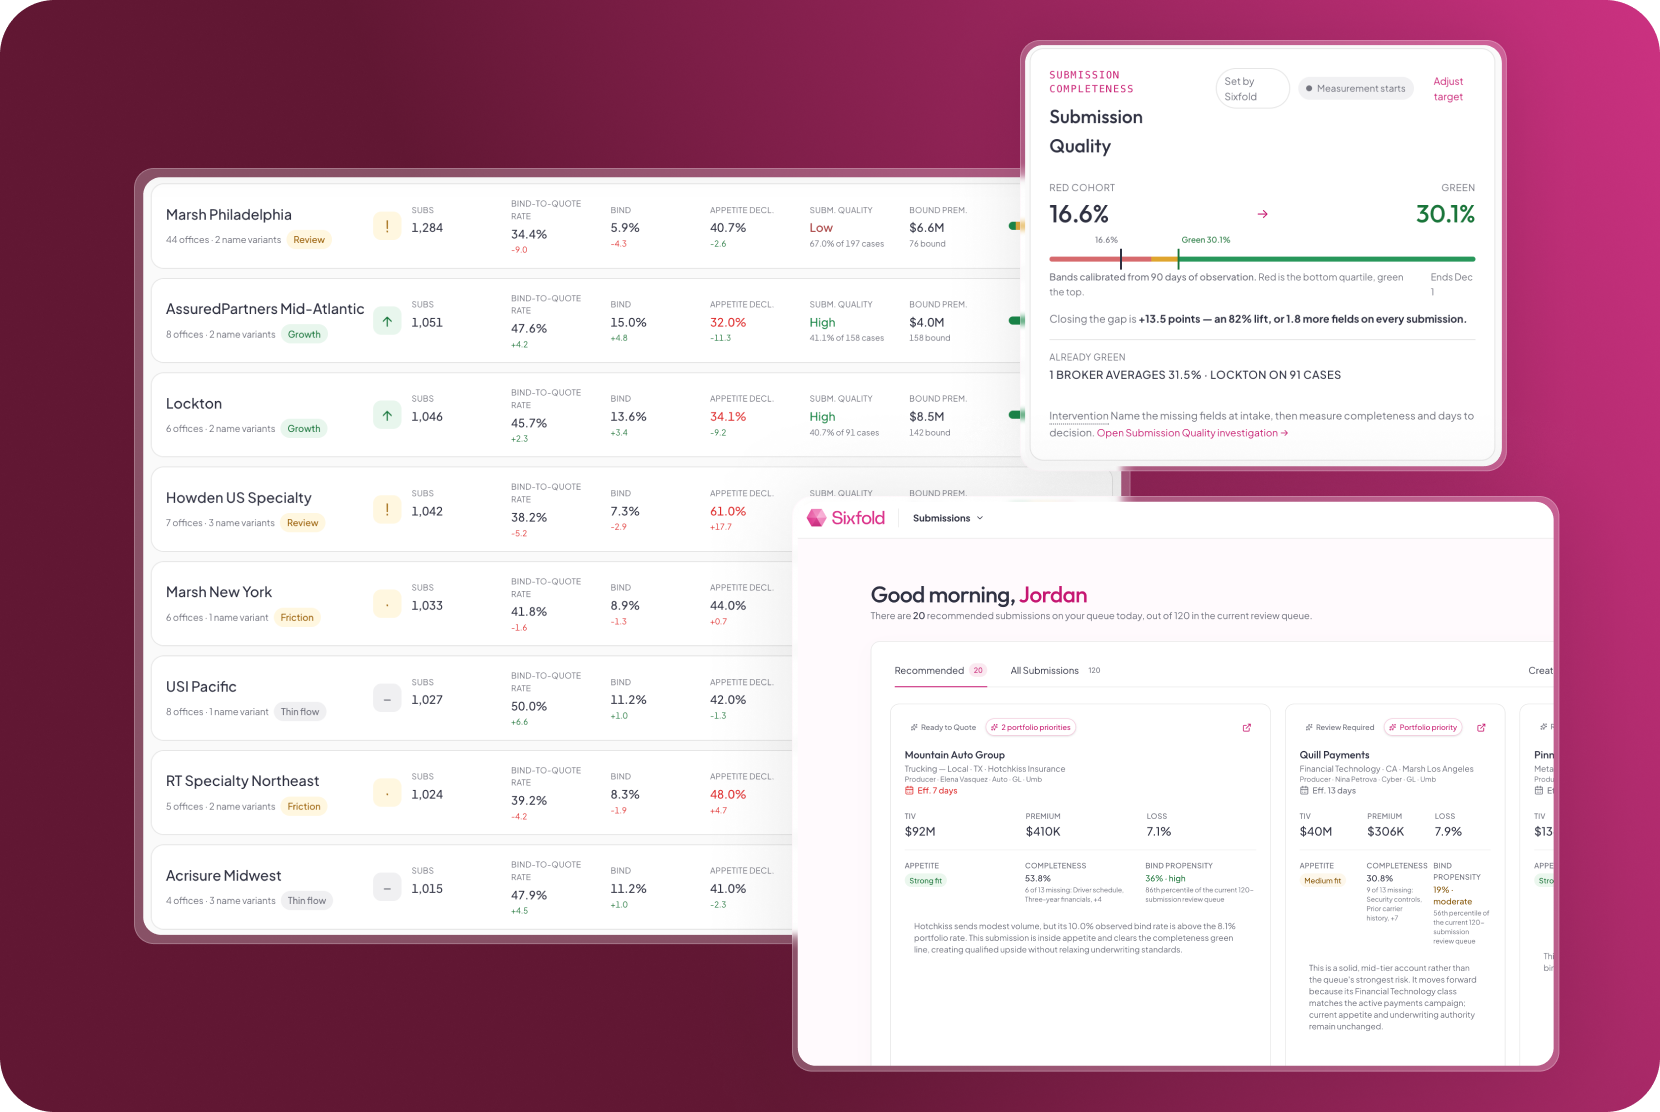
Sixfold provides an AI Underwriter for commercial P&C and for life and health, built on an underwriting knowledge base the company calls the Underwriting Brain. It evaluates submissions, learns each carrier's appetite, and proposes the next action on every case.
On the P&C side it covers property, excess and surplus, general liability, workers compensation, cyber, professional liability, D&O, commercial auto, employment practices liability, environmental, umbrella, inland marine, construction and surety. It runs standalone or plugs into an existing workbench or policy administration system.
Key features include:
- Submission extraction: Reads complex statements of values, loss runs and other submission documents, then pulls in online research and third-party data to fill gaps in the file.
- Appetite and portfolio evaluation: Assesses whether a risk fits the carrier's stated appetite and the current shape of the book, not just the risk in isolation.
- Explainable risk signals: Scores risk with signals where each fact is cited back to its source document, so the reasoning behind a recommendation can be checked.
- Next best action: Recommends what should happen next on each submission, from referral to higher authority to broker follow-up, and can execute where it has been given authority.
- Configurable autonomy: Carriers define what the system may do on its own by line, risk size and action type, with submissions stopping at any boundary that requires human approval.
- Life and health case analysis: Assesses prescription histories, lab results and driving records, surfaces key impairments with a suggested next step, and aligns rationale to the carrier's underwriting manual.
Limitations (based on publicly available sources):
- Underwriting-only scope: The product addresses underwriting rather than claims or policy servicing, so those workflows need separate coverage.
- Integration breadth: Third-party reviews have noted limited connections into core underwriting platforms, which makes integration fit worth confirming during evaluation.
- Carrier input required: Configuration depends on the carrier supplying underwriting guidelines and appetite documentation before the system can be tuned to its book.
- Company maturity: Sixfold was founded in 2023, so its track record is shorter than the established core system vendors in this category.
Source: Sixfold
12. hyperexponential (hx Renew)
Best for: Specialty and reinsurance teams pricing complex risk
Strengths: Actuarial pricing models wired directly into underwriting
Things to consider: Assumes actuarial capacity to build and maintain models
hyperexponential's hx Renew is a pricing and underwriting platform for specialty, commercial and reinsurance carriers. It brings actuarial pricing models into the underwriting workflow so a quote reflects the current model rather than a spreadsheet copy of it, and covers both submission triage and pricing and rating.
The platform combines model building, workflow configuration and portfolio analytics, with the same environment used by actuaries building models and underwriters pricing individual risks. It holds SOC 2 Type 2 and ISO 27001:2022 certification.
Key features include:
- AI-assisted ingestion: Captures data from Excel, PDF, Word, email and images to pre-populate pricing tools, removing manual rekeying between submission arrival and triage.
- External data enrichment: Enriches submissions at the point of pricing with third-party and internal data covering exposure, hazard and historical performance.
- Portfolio context during pricing: Surfaces portfolio insight while an individual risk is being priced, so underwriters can benchmark against existing business and spot accumulation or concentration.
- Underwriting Agent: Stress-tests rates, highlights portfolio drivers and answers underwriting questions in context, then turns model outputs into broker-ready and audit-ready narratives.
- Quote versioning and governance: Tracks every quote revision with version control, preserving assumptions, approvals and rationale across iterations for audit and compliance review.
- Model feedback loop: Flags market shifts and performance signals in-platform so actuaries can update models and deploy changes without leaving the environment.
Limitations (based on publicly available sources):
- Market focus: The platform is built for specialty, commercial and reinsurance lines, so personal lines and lending underwriting are outside its remit.
- Actuarial resource assumption: Models are built and maintained in a Python development environment, which assumes actuarial and technical capacity on the carrier's side.
- Enterprise scope: Deployment spans pricing, underwriting and portfolio analytics, which makes adoption a programme rather than a single workflow rollout.
- Pricing visibility: Pricing is not published and is scoped per carrier.
Source: hyperexponential
13. Gradient AI
Best for: Insurers scoring risk and claim severity from a shared dataset
Strengths: Risk scores, severity prediction and portfolio stratification
Things to consider: Analytics layer that plugs into existing underwriting systems
Gradient AI applies predictive models to a proprietary industry dataset for property and casualty, workers compensation and group health insurers. It scores applications for underwriting risk and flags claims likely to escalate, with the outputs embedded in existing day-to-day workflows rather than a separate interface.
The company reports an 80% decrease in quote turnaround time, a 10% reduction in average total incurred and a 44-day reduction in the duration of lost-time claims among its clients. It is SOC 2 compliant and HITRUST certified.
Key features include:
- Risk scores and severity predictions: Assigns scores to applications and claims so vulnerable files surface immediately rather than after the signs have compounded.
- Multidimensional data analysis: Combines economic, health, geographic and demographic data to build a risk profile that goes beyond what sits in the application itself.
- Portfolio stratification: Segments and displays exposure across the whole book, supporting margin protection and reserve adequacy decisions.
- Underwriting and risk selection: Supports pricing decisions, shortens quote turnaround and enables straight-through processing for low-risk applications.
- Claims triage: Identifies claims with potential high severity early so they can be assigned to experienced adjusters and resourced before costs build.
- Loss trend monitoring: Tracks emerging loss trends and exposure concentrations across the book, including when expanding into new geographies or lines.
Limitations (based on publicly available sources):
- Analytics rather than workflow: The product supplies predictive intelligence embedded into existing systems, so it does not replace an underwriting workbench or policy administration platform.
- Line coverage: The solutions are organised around group health and property and casualty including workers compensation, which narrows fit for other lines.
- Data dependency: Predictions draw on a proprietary dataset combined with client data, so value is tied to the volume and quality of the history available.
- Pricing visibility: Pricing is not published and is arranged through the sales process.
How Kolena handles real estate underwriting
Three things distinguish Kolena's approach within the AI-native category.
Inline citations and reasoning on every extraction. Every field Kolena extracts links back to the exact document, page, and section it came from — plus a short reasoning narrative explaining how the agent interpreted complex clauses. This is the difference between a tool an analyst can trust at investment committee and a tool that requires manual re-verification. It applies equally to acquisitions (verifying base rent against the lease) and lending (verifying loan terms against the borrower file).
Multi-model consensus for accuracy. Kolena validates extractions across multiple AI models and returns results only when they agree. This addresses the single biggest concern with applying AI to legal and financial work: hallucinations. By requiring consensus, the system catches the failure modes that break single-model approaches.
Batch document handling with template-first output. Rather than one document at a time, Kolena handles full deal packages — OM, rent rolls, T-12s, leases, amendments — as a single workflow. Output exports directly into the firm's existing Excel underwriting model, Yardi import sheets, IRR models, or downstream systems. No copying from chat responses; no re-formatting.
These three capabilities matter across every aspect of underwriting work — but they matter most where general-purpose AI fails: multi-amendment lease abstraction, complex rent table parsing, and high-volume borrower file review.
Customer case study: Real Capital Solutions
Real Capital Solutions is a private equity commercial real estate investment manager with $2.8 billion in assets under management across the US, Mexico, and Canada. The firm faced a familiar problem: manual lease review was slow, expensive, and inconsistent. Outsourced lease abstraction cost $375 to $450 per lease, and outputs varied in quality.
A recent acquisition — a mall with 150 tenants — made the problem impossible to ignore. The team needed fast, accurate economic data from leases and amendments to underwrite the deal. Internal reviews were taking two hours or more per lease.
After evaluating more than a dozen products, Real Capital Solutions implemented Kolena. Two technical hurdles consistently tripped up the alternatives: handling amendments and versioning (returning the current effective term across multiple documents rather than isolated answers per file), and reading rent tables natively (rather than collapsing tables into text and reconstructing them, which produced header errors and merged columns).
The results:
- Deployment in three days from contract to a working environment
- Internal review time dropped from two hours per lease to roughly seventeen minutes — an 85% reduction
- Use cases expanded beyond acquisitions to fee agreements (asset management billing), commercial loan documents (DSCR testing and debt forecasting), tax notice processing, and rent roll reconciliation across multiple property managers
- Non-technical paralegals and property accountants could create new agents in 10-minute intro sessions
A direct quote from the firm captures the strategic effect: "Kolena AI allows us to be more in a decision-making stance instead of spending half our life finding data."
The full case study covers the deployment, integration, and ROI calculation in more detail.
Frequently asked questions
What is real estate underwriting software?
How is AI-native underwriting software different from using ChatGPT?
Is AI underwriting accurate enough for institutional decisions?
How much does real estate underwriting software cost?
Can underwriting software replace an analyst?
What's the difference between Kolena and other AI underwriting tools?
Next steps
Most firms evaluating real estate underwriting software in 2026 are not replacing a single tool — they're adding an AI extraction layer that feeds the rest of their stack. The right way to evaluate any platform is with the firm's actual documents: a representative set of leases, rent rolls, and T-12s, mapped against the firm's own underwriting template. That test reveals what's real and what's demo magic.
If your team handles document-heavy underwriting on either the equity or debt side, request a Kolena demo with your own deal documents, or try the platform free for 2 weeks.